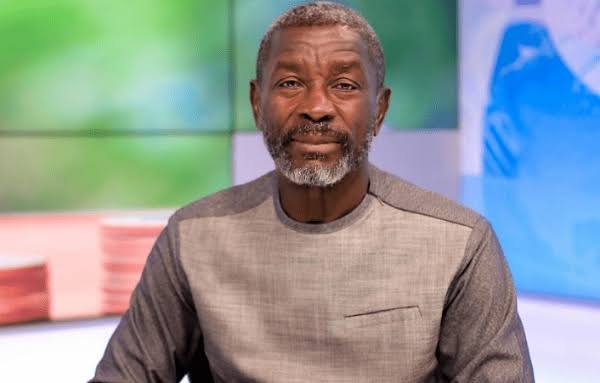
Retired military officer and businessman Captain Prince Kofi Amoabeng has spoken about some of the internal challenges he says contributed to the difficulties faced by his former financial institution, UT Bank.
Amoabeng, who founded UT Financial Services before it expanded into banking, made the revelations while reflecting on the rise and eventual collapse of the institution. His account focused on what he described as breaches of trust involving people who had been given significant responsibilities within the organisation.
Among the incidents he recalled was an alleged demand for a US$200,000 payment from a borrower by some officers associated with the institution.
According to reports of his interview, Amoabeng said the alleged demand was among the experiences that caused him to question the conduct of individuals he had trusted to protect the interests of the business.
Alleged $200,000 demand
Amoabeng reportedly explained that the incident involved employees dealing with a borrower who was seeking financial assistance.
He said the officers allegedly sought $200,000 in connection with the transaction, raising concerns about the way some members of staff were conducting business.
The businessman presented the episode as an example of the difficulties that can emerge when a growing organisation becomes dependent on individuals who may not always operate in accordance with its established principles.
His comments form part of a wider reflection on the management problems, loan decisions and internal weaknesses that he believes affected UT as it developed from a relatively small financial services company into a major Ghanaian financial institution.
Concerns over property used as loan security
Amoabeng also reportedly discussed a separate loan-related matter involving a property that he considered unsuitable collateral.
The building, according to the account, was situated on what he described as marshy or problematic land. Despite concerns surrounding the property, a loan was allegedly approved using it as security.
The episode, he suggested, demonstrated how decisions taken by individual officers could create serious financial exposure for an institution.
For Amoabeng, the issue was not simply about one questionable transaction. It reflected the broader challenge of maintaining strong internal controls as a business grows and responsibilities are delegated to different levels of management.
Trust and the growth of UT
Amoabeng’s reflections also touched on the personal side of building UT.
The institution began as Unique Trust Financial Services and eventually became one of Ghana’s prominent indigenous financial companies. Amoabeng has previously spoken about the entrepreneurial decisions, regulatory challenges and financing pressures that accompanied the company’s expansion.
In the recent interview, he looked back at the people who worked around him and the extent to which he relied on trusted employees to execute decisions on behalf of the organisation.
The businessman suggested that some of the problems he encountered were particularly painful because they involved individuals who had been entrusted with important responsibilities.
UT Bank’s difficult final years
UT Bank became one of several Ghanaian banks whose licences were revoked during the country’s banking-sector crisis.
The Bank of Ghana revoked UT Bank’s licence in August 2017 after determining that the institution had a significant impairment of its capital. GCB Bank subsequently took over certain assets and liabilities as part of measures to protect depositors.
The collapse marked a major turning point for Amoabeng, whose business had grown from a financial services operation into a well-known banking brand.
The events surrounding UT Bank have remained an important part of his public reflections, particularly regarding corporate governance, lending decisions, management and the pressures associated with building large financial institutions.
Lessons from the experience
Amoabeng’s latest comments also offer a window into the lessons he believes can be drawn from his experience.
In other recent discussions, he has encouraged entrepreneurs to establish strong systems early, exercise discipline and understand the business environment in which they operate.
His account of the alleged $200,000 demand and the disputed property used as collateral similarly highlights the importance of effective oversight in financial institutions.
For businesses handling large sums of money, internal controls, transparent approval processes and accountability can play a crucial role in limiting the impact of individual misconduct.
Amoabeng’s recollection therefore goes beyond the story of one company. It forms part of his broader examination of the decisions, relationships and institutional challenges that shaped his decades-long journey as an entrepreneur.
While UT Bank’s collapse remains a significant chapter in Ghana’s banking history, Amoabeng’s recent reflections show that the experience continues to influence how he views leadership, trust and the building of sustainable businesses.