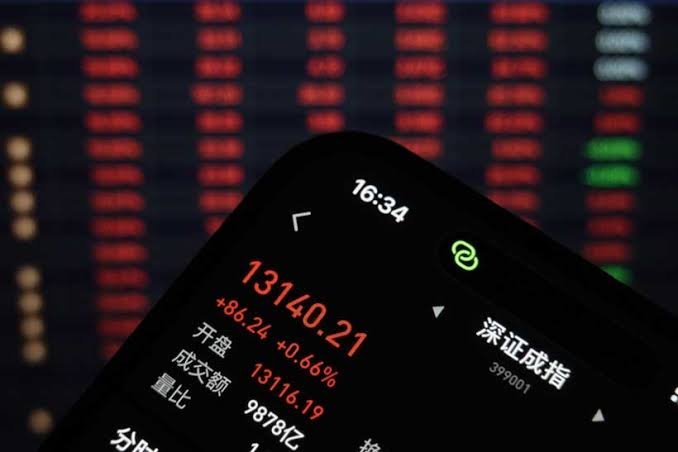
Asian stock markets moved lower on Friday as investors remained unsettled by sharp movements in global bond and currency markets while awaiting fresh US employment figures that could influence the Federal Reserve’s next interest-rate decision.
The market uncertainty followed a turbulent session for government bonds, with US Treasury yields reaching levels not seen in more than two decades before easing back. Investors are also watching elevated oil prices and rising geopolitical tensions in the Gulf, adding to concerns about inflation and borrowing costs.
Asian Stocks Under Pressure
MSCI’s broadest index of Asia-Pacific shares outside Japan was down about 0.5% and was heading towards a weekly decline of roughly 1.7%.
Japan’s Nikkei also weakened, falling 1.1% during the session. The declines came as investors reassessed the outlook for interest rates and the health of the global economy.
Markets in mainland China were closed for a public holiday, limiting trading activity in the region.
Meanwhile, US stock futures pointed towards a modestly stronger opening. Nasdaq futures were up around 0.5%, while S&P 500 futures gained about 0.3%. European stock futures were also indicating a slightly firmer start to trading.
US Jobs Report in Focus
The biggest event for investors was the US government’s September employment report.
Economists surveyed by Reuters were expecting the US economy to have added about 90,000 jobs during the month, while the unemployment rate was forecast to remain at 4.1%.
The figures could influence expectations surrounding the Federal Reserve’s interest-rate policy.
A stronger-than-expected employment report could reinforce expectations that the central bank may consider another rate increase this month. However, traders had placed the probability of an October increase at only about 25% before the data was released.
The Federal Reserve raised rates by 25 basis points in September, its first increase since 2023, and policymakers have indicated that further decisions will depend heavily on incoming economic data.
Treasury Yields Reach Multi-Year Highs
The US bond market has become a major source of concern for investors.
The benchmark 10-year Treasury yield climbed to 5.34%, its highest level since 2002, before retreating to around 5.25% during Asian trading.
The move came after the yield recorded its biggest quarterly increase in more than three decades, highlighting the growing pressure facing global fixed-income markets.
Higher government bond yields can affect borrowing costs across the economy and can also make equities less attractive relative to fixed-income investments.
The recent rise has been linked to concerns about inflation, government borrowing and the possibility that central banks may keep interest rates higher for longer.
Dollar Gains While Euro Struggles
Currency markets have also been affected by the recent volatility.
The US dollar was heading towards a third consecutive weekly gain and had reached its strongest level in about 18 months, supported by relatively high US yields and stronger economic expectations.
The euro, meanwhile, came under pressure because of growing concerns over public finances and political uncertainty in France.
The common European currency fell as low as $1.1215, its weakest level since May 2025. The euro also lost ground against the Japanese yen and Swiss franc.
France’s fiscal difficulties have become an additional source of concern for investors, with the gap between French and German government bond yields widening to levels last seen in 2012.
Oil Prices Keep Inflation Concerns Alive
Energy markets remain another major factor influencing investor sentiment.
Oil prices have stayed elevated as military tensions in the Gulf raise concerns about energy supplies. The wider US military buildup in the region has added to uncertainty surrounding future oil flows.
Higher crude prices could put renewed upward pressure on inflation, making it more difficult for central banks to reduce borrowing costs.
Reuters reported that Brent crude had remained above $100 a barrel amid the broader market concerns, adding another complication for policymakers and consumers.
Wall Street Shows Some Resilience
Despite the pressure in Asian markets, US equities showed signs of resilience in the previous session.
The S&P 500 recovered from earlier losses to finish 0.23% higher at 7,668.82, while the Nasdaq Composite added 0.07% to close at 26,871.60. The Dow Jones Industrial Average gained 0.06% to 50,935.89.
The rebound followed a reversal in Treasury yields, which helped ease some of the pressure on stocks.
Energy shares were among the strongest performers after oil prices jumped, while technology stocks also advanced. Micron Technology gained after delivering a stronger revenue outlook and announcing substantial customer commitments tied to its supply agreements.
Investors Await Clearer Direction
Markets are now balancing several competing forces, including elevated inflation risks, high government borrowing costs, geopolitical tensions and uncertainty over the Federal Reserve’s next move.
The US employment figures are expected to provide an important indication of whether the economy remains strong enough to withstand tighter monetary policy.
For investors, the combination of volatile bonds, shifting currency markets and expensive energy means the outlook remains highly sensitive to incoming economic and geopolitical developments.
With central banks still focused on inflation and borrowing costs at elevated levels, global financial markets are likely to remain particularly responsive to economic data in the weeks ahead.